Guide
Water damage or flood: which policy applies
Two houses can have the same wet carpet and two different insurance situations. The difference is where the water came from.
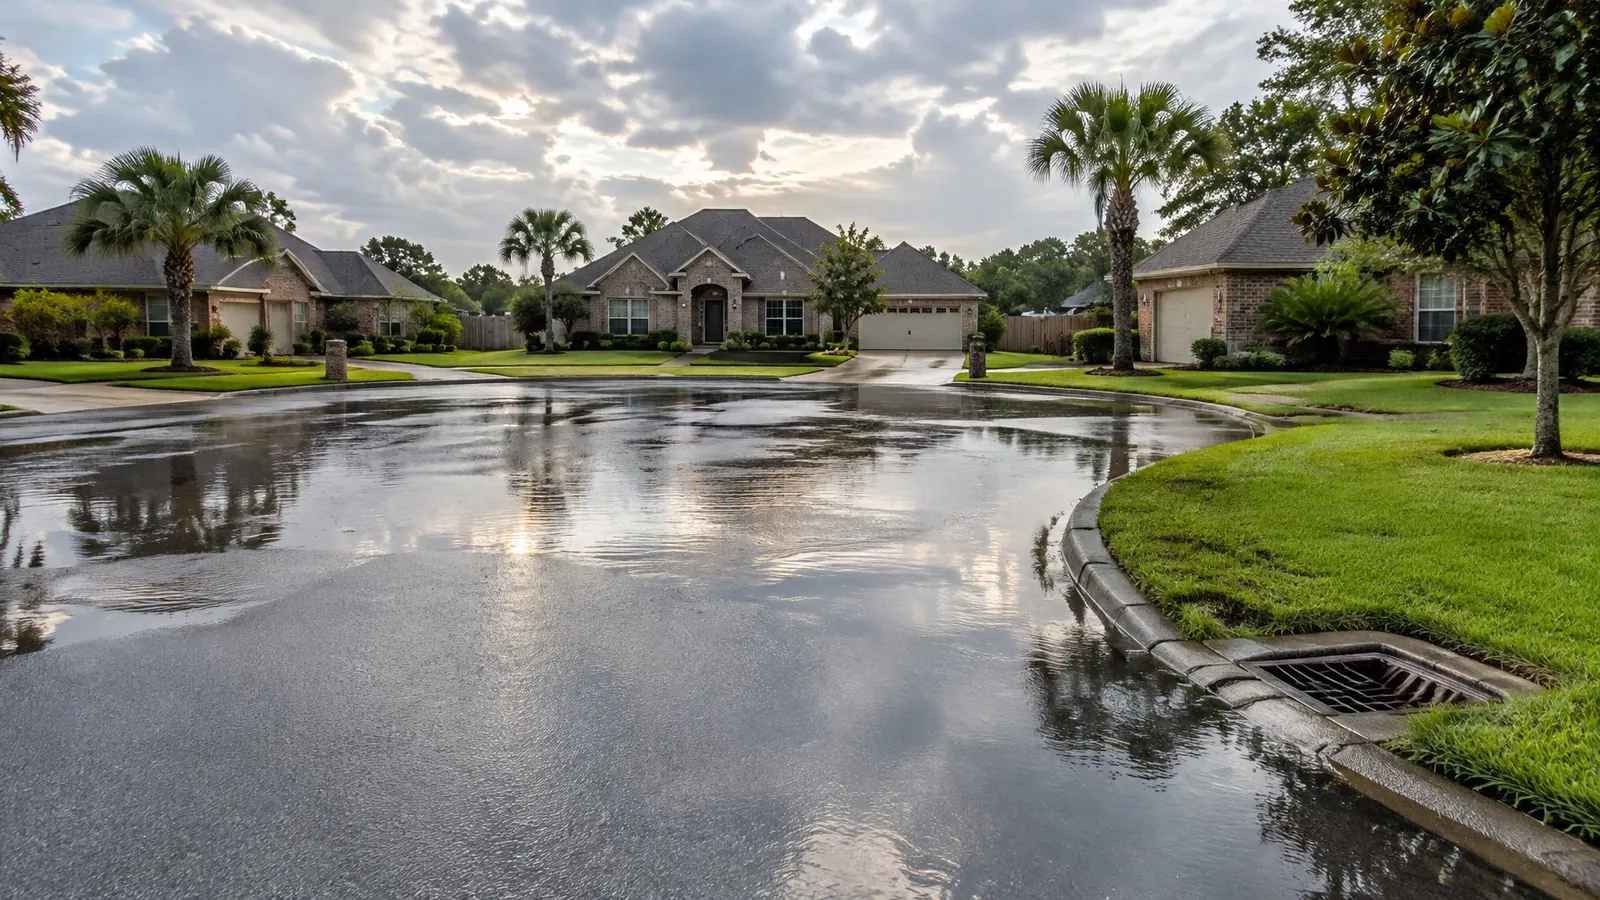
Two sources, two policies
Water that escaped from inside the plumbing system, such as a burst pipe or a failed hose, is a home policy matter. TDI says a sudden and accidental release of water is generally covered.
Water that entered from outside and spread over the ground is flooding. TDI says most home policies exclude it and that a separate flood policy is needed.
A storm can cause both in one night: a roof leak and a flooded garage. Each is looked at separately.
The waiting period
According to TDI, most flood policies have a 30-day waiting period. A policy bought after the forecast turns bad will not respond to that storm.
The National Flood Insurance Program lists providers at floodsmart.gov.
Where Missouri City sits on the maps
The city says it worked with Fort Bend County, Harris County and FEMA on the official flood insurance rate maps. The Fort Bend County maps are effective as of 2 April 2014. The Harris County maps and flood insurance study took effect on 9 June 2014.
It also links an interactive floodplain map so you can look up an address. Start at Floodplain Maps.
A practical split
- Pipe, hose or tank failed: ask your home insurer.
- Rain came in through the roof: ask your home insurer.
- Rain or river water came in at ground level: ask your flood insurer, if you have one.
- Sewer backed up: check whether the home policy has the backup add-on.
Water is still moving. Call about it now.
Describe what happened, give the street address, and the call is routed to an independent restoration contractor.